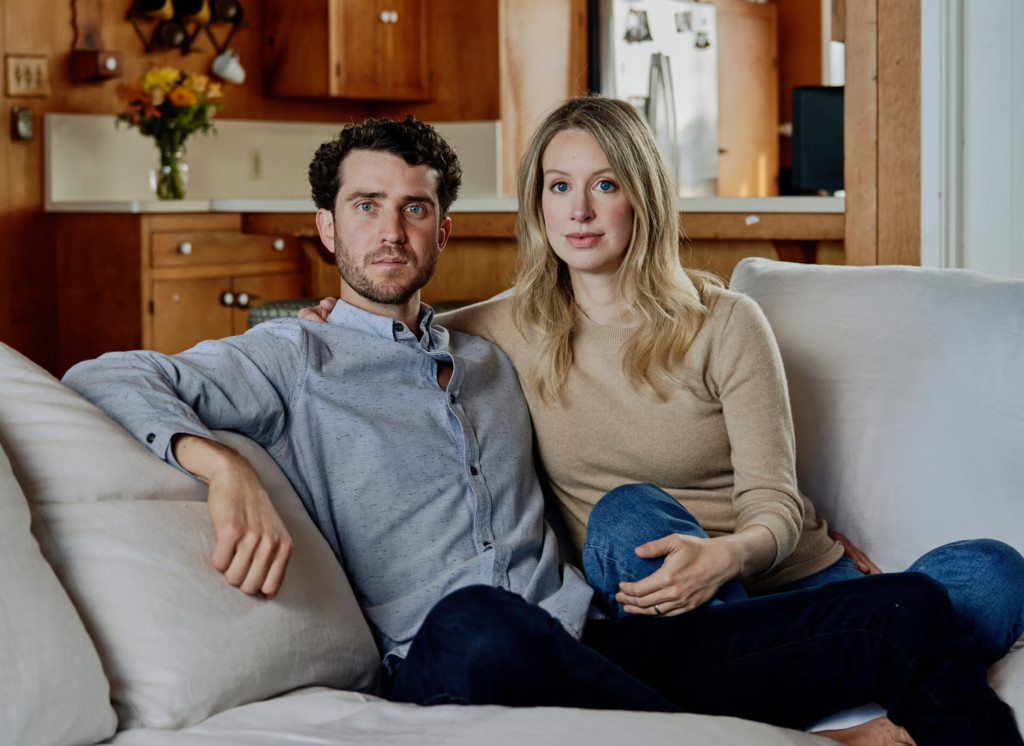
I saw “You can see everything” with my wife on our date night last Friday. We both really liked it, and were puzzling away on the drive home about who said what to whom, who we thought was likely lying or truthful, what Elizabeth Holmes’ partner Bill Evans was really up to, whether Nathan Fielder (the journalist) was going to lunge and kiss Holmes (former CEO of Theranos) when she was hitting him with the puppy dog eyes, etc. We both knew of the events regarding Theranos generally, but were not well acquainted with the particulars prior to the movie, which probably made for better entertainment. 🙂
If you haven’t seen it yet, the movie is a meta-documentary that did a great job of immersing you in Holmes’ and Evans’ personal circumstances with their two young kids in the weeks prior to her having to report to prison in Texas in 2023 for defrauding investors out of hundreds of millions of dollars. It delves into Holmes’ and Evans’ claims of her innocence regarding her over-reaching/fraudulent statements about the company’s microfluidic blood analysis technology and its capabilities. SPOILER ALERT!! Fielder focussed on whether Holmes was intentionally deceiving people (i.e. investors, the public) when, in years past, she said things to the effect of ‘the product can do a multitude of tests simultaneously’. He was trying to determine whether she genuinely didn’t understand that this phrase would be interpreted by most to mean “the product has already successfully and conclusively demonstrated its ability to do a multitude of tests …”, not “the product can, in theory and once fully developed, do any and all of a multitude of tests …”. To get a better read on her interpretation of her own words, he gets her interpretation of the “Who’s on First” skit by Abbott and Costello, where her answers suggest that, by virtue of her very literal interpretation, she misses the double ententes that are the essence of the humour. They touch on whether she is neuro-divergent, and leave the audience to draw their own conclusions.
The next morning, my wife and I were still sorting out all the loose ends during our dog walk. We discussed who we now believed to be truthful, and my wife was asking me about the microfluidics, analytical chemistry and business aspects of the story. This is also where my thoughts had led to, and is the reason I’m writing this article.
The short version of this post’s analysis can be summarised as follows: there’s no way the Theranos calamity would have happened had robust technical due diligence been performed. It can be put even more succinctly using the Russian proverb that the late President Reagan was fond of: trust, but verify.
As a microfluidics consultant who a) supports technology development projects, and b) performs technical due diligence investigations on behalf of prospective investors, I can tell you that I was dumbfounded as to how this situation could have arisen in the first place. While the trustworthiness of the leadership team at Theranos (or any company) would have been crucial to investor decision-making, so too should have been the imperative for, and results from, a rigorous technical due diligence investigation. My astonishment lead to a deeper dive into the events surrounding the rise and fall of Theranos, and especially into investment rounds that totalled over $900M USD from venture capitalists (VCs) and companies like Safeway and Walgreens.
It turns out I’m very late to the party; much has been written on this very point. If you’re interested in the business and investment angle of the story, there is a pretty good Wikipedia entry for Theranos. and below are some references that explore various aspects of this story, including legal references, investigative journalism, an on-site interview video, and retrospective analyses and opinions on problems and failure modes.
- Wall Street Journal exposé on Thereanos’ inconsistent product performance, secrecy and fraudulent practices that kicked off the firestorm of trouble for the company (John Carreyrou, October 15th, 2015):
- Wall Street Journal exposé on Walgreens’ investment in Thereanos despite its misgivings due to secrecy regarding product performance (Christopher Weaver and John Carreyrou, May 25th, 2016):
- CNN video tour of Theranos and interview with Holmes (Sanjay Gupta, August 1st, 2016):
- Editorial in the European Journal of Clinical Investigations criticising stealth (i.e. unpublished) research by start-up ‘unicorns’ (VC backed with valuations over USD $1B) (Ioana Cristea et al., April 1st, 2019):
- Editorial post mortem in the Journal of Medical Systems regarding the rise and fall of Theranos, highlighting steps such as encouraging engagement in academic collaborations, publication of scientific results, and revitalised investor due diligence (Rishub Das et al., April 4th, 2022)
- Lexology blog post regarding the importance of due diligence in light of Holmes’ fraud conviction (Ellen Lambrix, Bristows LLP, January 5th, 2022)
- Vaultinum blog post regarding Theranos’ secretive practices, unproven technology, and the importance of technical due diligence as an inoculant against future such travesties (Marine Yborra, May 18th, 2022)
- Legal summary for U.S. v. Elizabeth Holmes, et al., provided by the US Attorney’s Office, Norther California.
The answer to my question about how this could ever have come to be is essentially two-fold. Several top VC inventor firms refused to get involved when their attempts to perform technical due diligence were thwarted by Theranos’ insistence on secrecy, which they claimed was based on their need to protect their intellectual property (see reference 7). Other investors either didn’t bother trying to look that deeply, or weren’t willing to push Theranos to either a) expose its technology to scrutiny, or b) at least demonstrate product performance through independent testing against gold standard analytical methods. Walgreens investigative consultants were denied access and reported their reservations, but Walgreens persevered (see reference 2).
In the investment due diligence investigations I have performed, the start-ups have confidentially revealed all of their performance data, reports, and intellectual property (IP), and they have fully answered my innumerable questions about all aspects of their microfluidic devices, analytical instrumentation, protocols and procedures, and the performance achieved. This has allowed me in each case to write a detailed and accurate report for my client—the prospective investor—that fully described the extent to which IP, technology, performance, and the leadership team were evaluated, the findings in each of these areas, and my analysis and recommendations based on those findings. Some start-ups get rosier recommendations than others, naturally, but I have had full disclosure in all cases. Had I been met with resistance to supply information, I would have questioned the target company as to why, and then I would have clearly highlighted the resistance, missing information, and associated enormous risks in the report.
Thorough technical due diligence for investment in a deep tech-based company like Theranos should be regarded as mandatory by investors, not optional. I should note that I have not dealt with unicorn start-ups with their very aggressive growth curves, valuations, and leadership teams that are secretive about their technology. While I understand that a unicorn investment target represents a significant paradigm shift compared to a ‘normal’ start-up, and that a change in approach might be required for a technical due diligence investigation, the fundamental requirement of verifying product technology and performance must still be met. There really are no valid explanations or excuses that justify a lack of disclosure, or demonstration of performance; asking an investor to ‘take their word for it’ doesn’t pass muster. Suitable non-disclosure agreements (NDAs) can be used to safeguard the target company’s IP when revealed to the prospective investor or their consultant. Failing that, and at a minimum, performance comparisons against gold standard chemical analysis methods can still be demonstrated, even it the technology in question is treated as a secret black box to protect IP.
A lack of published results underpinning a technology does not prove the technology is faulty, but is a red flag, in my view. The increasing tendency of technology-based start-up unicorns to bypass the rigours of publishing their work in refereed journals is documented in references 4 and 5. Reluctance to publish is understandable in the context of a start-up with fast-approaching milestones and limited resources, as it is admittedly laborious and provides some level of potentially undesirable visibility into the nature of their technology. On the other hand, the process of publishing one’s work requires that the intended level of performance be obvious, robust and reproducible, which is in the interests of both the start-up and investor, and has been a successful approach for many start-up unicorns in the last decades.
My advice to investors? Review this cautionary tale about Theranos, and understand that the primary failure mode that led to the loss of mountains of money was not the fraud committed by Theranos’ leadership to cloak the inadequate performance of their product (horrible as that was), but was largely the failure on the part of investors to insist that technical due diligence be performed before the money flowed. Proper due diligence will expose whether performance results are excellent, modest, poor, or hidden, and enables the investor take appropriate action. In the case of hidden results, I recommend not investing!